All balances making up the indicator contributed to the increase. The business climate rose sharply in transport equipment manufacturing, while the balance of opinion on personal production prospects increased for the third consecutive month, moved further above its long-term average and reached its highest level since February 2022.
The balance for the change in past production increased again but remained below its average. General production prospects in manufacturing rose for the sixth consecutive month and returned to their long-term average. The balance for economic uncertainty felt by business leaders rose sharply and returned to levels close to those seen in April and May, above its average.
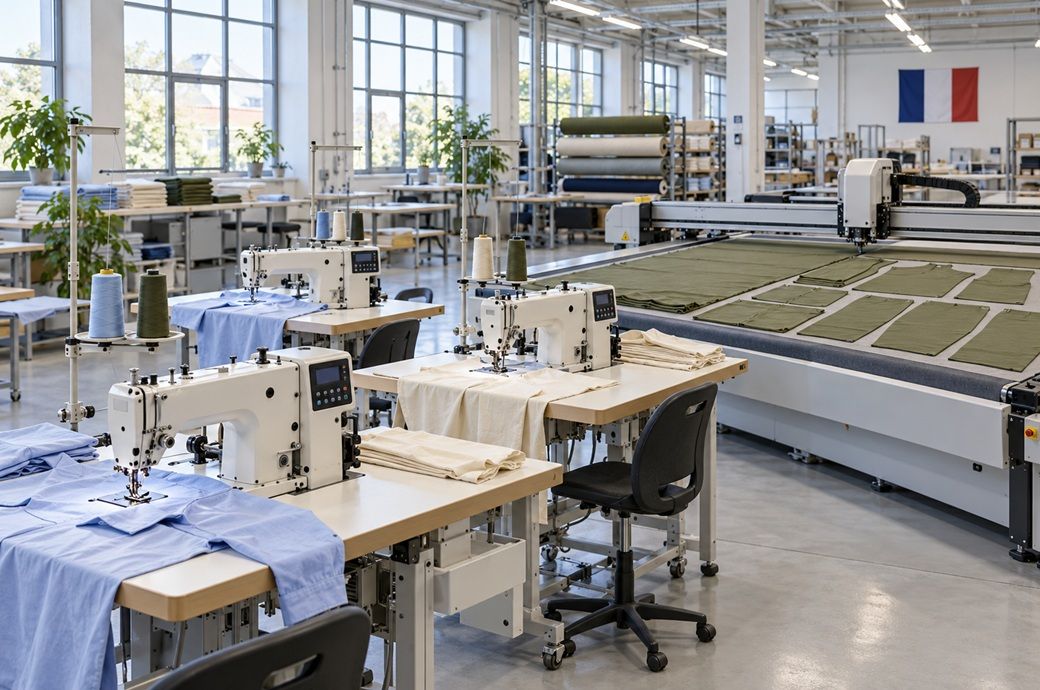
France’s manufacturing business climate rose four points to 105 in October 2026, moving further above its long-term average of 100.
Global and foreign order books strengthened; foreign orders were the highest since April 2022 and transport equipment rose to 111.
Supply-side obstacles stayed high at 31 per cent, while machinery and equipment improved to 107.
Order-book indicators strengthened in October. The balance for global order books rebounded and moved away from its long-term average, while the foreign order-book balance increased again, stood markedly above its average and reached its highest level since April 2022, the INSEE said in a press release.
The balance of opinion on finished goods inventories fell back below its average. Workforce balances, both past and expected, slightly rebounded and stood above their long-term averages. The balance for expected selling prices over the next three months fell back but remained well above its average, which it has exceeded since February 2026.
Production obstacles remained a watch point for manufacturers. The share of companies reporting production obstacles due to workforce shortages was stable, one point above its average. The share reporting sourcing difficulties as a limiting factor rose slightly and has been well above its own average since July 2025.
Overall, the share of companies declaring supply-side obstacles only was stable at 31 per cent, well above its average. The share declaring demand-only obstacles was also stable, at 22 per cent, and remained very markedly below its average. The share reporting obstacles linked to both supply and demand edged down slightly.
In machinery and equipment goods manufacturing, the synthetic business climate indicator improved, mainly due to a sharp rise in the foreign order-book balance, which reached a level not seen since March 2023. At 107, the indicator moved further above its long-term average. Within the grouping, the indicator was stable and far above average in computer, electronic and optical products, increased again in machinery and equipment, and rebounded in electrical equipment.
Transport equipment recorded the strongest sectoral improvement. Its business climate indicator rose sharply to 111, moved further above its long-term average of 100 and reached a level not seen since last January. In motor vehicles, trailers and semi-trailers, the indicator fell slightly but remained one point above its average; a strong increase in the past-production balance did not offset downturns in global and foreign order-book balances.
By contrast, the business climate increased very markedly again in other transport equipment manufacturing, moving even further above its average. The rise was driven by balances relating to global and foreign order books.
The business climate indicator in “other manufacturing” was stable at 99, one point below its long-term average. All sub-sector climates decreased except the chemical industry, where the indicator increased by one point.
Fibre2Fashion News Desk (SG)