Net sales rose 0.9 per cent year on year (YoY) to ¥56.09 billion (~$355.37 million, as per conversion rate of $1 = ¥157.8355 as on November 6, 2026) in the six months ended September 30, 2026. Gross profit increased 3.7 per cent to ¥29.60 billion (~$187.54 million), while the gross margin improved by 140 basis points to 52.8 per cent. However, selling, general and administrative expenses rose 15 per cent to ¥24.84 billion (~$157.38 million), causing operating profit to fall 31.7 per cent to ¥4.76 billion (~$30.16 million).
Japan’s Goldwin reported a 0.9 per cent rise in H1 FY27 sales to ¥56.09 billion (~$355.37 million), while operating profit fell 31.7 per cent to ¥4.76 billion (~$30.16 million).
Gross margin improved to 52.8 per cent.
The group lowered its FY27 sales forecast to ¥141.50 billion (~$896.50 million) and operating profit outlook to ¥23.80 billion (~$150.79 million), citing weak demand and delivery delays.
Ordinary profit declined 15.4 per cent to ¥7.69 billion (~$48.72 million), while profit attributable to owners of the parent fell 18.9 per cent to ¥5.51 billion (~$34.91 million). Basic earnings per share (EPS) were ¥40.28 (~$0.26), compared with ¥49.56 (~$0.31) a year earlier, Goldwin said in its consolidated financial results.
Direct retail and e-commerce support margin expansion
Sales at directly managed stores and Goldwin’s own e-commerce site exceeded the prior-year level, supported by a focus on all-weather products led by THE NORTH FACE. The higher mix of these high-margin channels lifted gross margin despite increased discounting and inventory valuation losses.
THE NORTH FACE recorded solid demand for rainwear, including the Mountain Light Jacket and Climb Light Jacket, FLASHDRY functional products and baby shell blankets. Sales of T-shirts, cut-and-sewn products and standard logo merchandise were weak, however, while wholesale revenue declined amid lower buy-out orders from sporting goods retailers, delayed deliveries of certain products and softer inbound tourism demand.
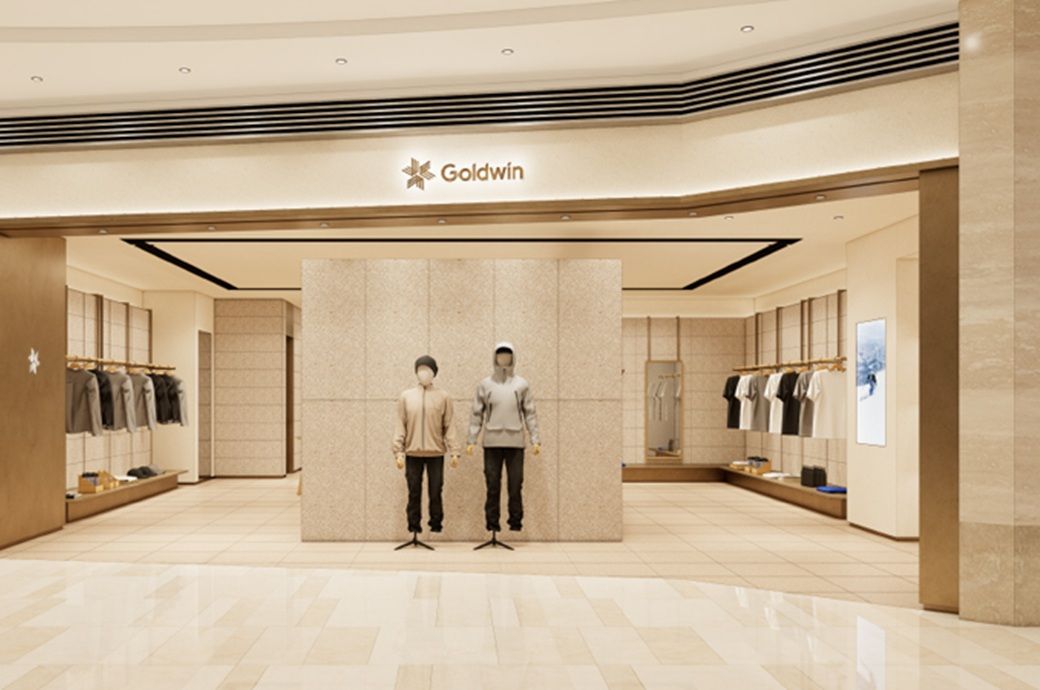
The Goldwin brand saw steady sales at its Marunouchi, Harajuku and Kyoto directly managed stores and through e-commerce after strengthening coordination between products, sales floors and customer service from late August. Higher personnel, rent, logistics and sales promotion costs associated with store openings and renovations weighed on operating profit.
Balance sheet remains strong despite lower cash
Total assets stood at ¥167.39 billion (~$1.06 billion) as of September 30, 2026, compared with ¥168.23 billion (~$1.07 billion) at March-end. Net assets increased to ¥132.37 billion (~$838.66 million) from ¥130.50 billion (~$826.81 million), lifting the equity ratio to 78.3 per cent from 76.9 per cent.
Cash and cash equivalents fell to ¥45.18 billion (~$286.25 million) from ¥50.96 billion (~$322.87 million) at the start of the fiscal year. Operating activities generated ¥697 million (~$4.42 million), while investing activities used ¥2.33 billion (~$14.76 million), including ¥2.05 billion (~$12.99 million) for property, plant, equipment and intangible assets. Financing activities used ¥4.28 billion (~$27.12 million).
Goldwin lowers FY27 sales and earnings forecast
For the year ending March 31, 2027, Goldwin lowered its forecast to net sales of ¥141.50 billion (~$896.50 million), representing growth of 2.9 per cent YoY and a 2.7 per cent reduction from its previous outlook. It expects operating profit of ¥23.80 billion (~$150.79 million), down 8 per cent YoY and 8.8 per cent below its earlier forecast; ordinary profit of ¥32.50 billion (~$205.91 million), down 4.1 per cent YoY; and profit attributable to owners of the parent of ¥24.30 billion (~$153.96 million), up 0.9 per cent YoY. Forecast EPS are ¥177.63 (~$1.13).
The revision reflects the first-half shortfall caused by unfavourable weather, weaker inbound tourism, delayed autumn demand at retailers and delivery delays for some products. Goldwin said it would pursue second-half growth through sales of heavy apparel and functional products, wholesale shipments linked to in-store sales, lower purchases of ongoing products and new Goldwin stores in Ginza and Fukuoka, alongside THE NORTH FACE’s 60th-anniversary activities.
Fibre2Fashion News Desk (MS)