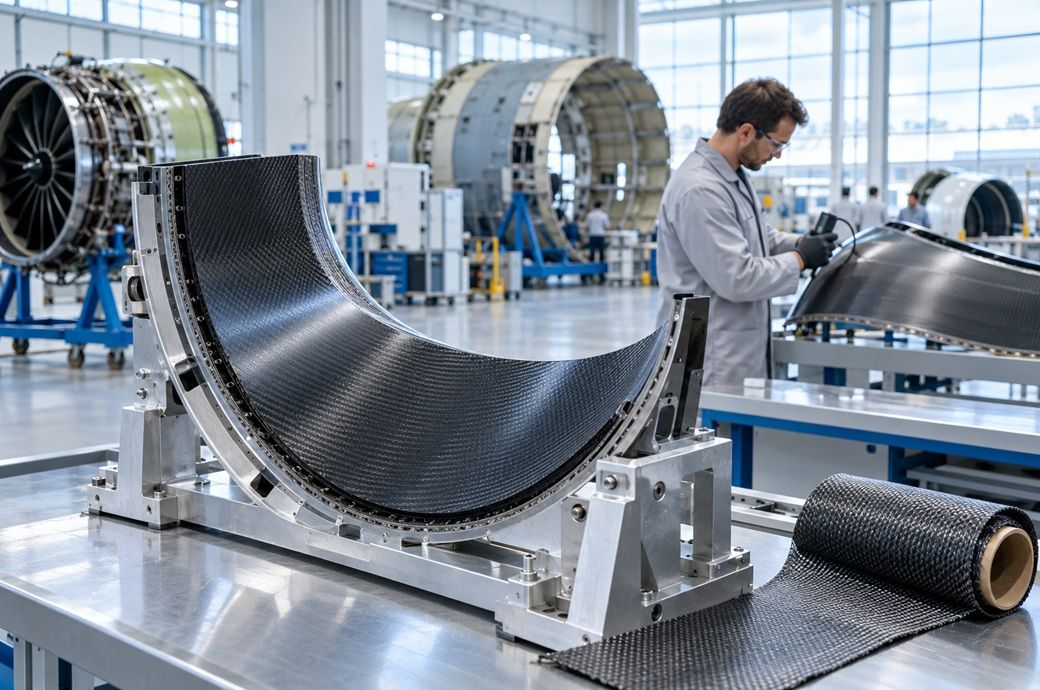
The company said it is shifting its focus from legacy issues towards aerospace and defence opportunities, including missiles, hypersonics, space and next-generation aircraft applications.
Albany International has set fourth-quarter revenue guidance after a third-quarter turnaround led by Engineered Composites and CH-53K contract modifications.
Third-quarter revenue rose 34 per cent year on year to $349.5 million, while net income reached $41.7 million against a prior-year loss.
Adjusted EBITDA was $100.1 million and free cash flow increased to $36.5 million.
Net revenue rose 34 per cent year on year (YoY) to $349.5 million in the third quarter ended September 30, 2026, from $261.4 million. Net income attributable to the company was $41.7 million, or diluted earnings per share (EPS) of $1.46, compared with a net loss of $97.8 million, or a diluted loss per share of $3.37, a year earlier.
The operating income reached $59.4 million against an operating loss of $116.5 million, while adjusted earnings per share rose to $1.68 from a loss of $3.29. Adjusted earnings before interest, tax, depreciation and amortisation (EBITDA) was $100.1 million, compared with negative $91.1 million in the prior-year quarter.
“I’m incredibly proud of the performance of the team in the third quarter. The team, with Engineered Composites leading the way, was able to favourably finalise the strategic review of our Amelia Earhart Drive facility in under a year and end the quarter with solid performance,” said Gunnar Kleveland, president and chief executive officer, Albany International Corp.
“In Machine Clothing, our team navigated a dynamic market environment and delivered sales at the high-end of expectations, reflecting the resilience of the business and the strength of our team,” said Kleveland.
Engineered Composites drives revenue growth
Engineered Composites revenue increased 107 per cent on a constant-currency basis to $179.7 million, driven by commercial and defence programmes, notably the LEAP, CH-53K and missile programmes. Its adjusted EBITDA margin improved to 36.5 per cent from negative 155.5 per cent a year earlier, reflecting CH-53K contract modifications, higher volumes and improved efficiency, Albany International said in a press release.
Machine Clothing revenue declined 3 per cent on a constant-currency basis to $169.8 million, primarily due to cyclical declines in the Americas. Its adjusted EBITDA margin fell to 27.2 per cent from 31 per cent, owing to volume and geographic mix, although the business saw steady conditions in Asia and improving volumes in Europe.
Margins recover on CH-53K modification
Gross profit was $140.4 million, compared with a gross loss of $49.9 million in the prior-year quarter, lifting gross margin to 40.2 per cent from negative 19.1 per cent. The result included a $33.4 million favourable gross-margin adjustment from CH-53K contract modifications, partly offset by catch-up depreciation and amortisation. The prior-year result included a $147.3 million unfavourable CH-53K loss-reserve adjustment.
The strategic review conclusion generated a $44.4 million adjusted EBITDA benefit related to the CH-53K contract modification. Selling, general and administrative expenses increased to $61.5 million from $51.9 million, chiefly due to compensation and strategic-review costs, while restructuring expenses rose to $7.3 million from $3.2 million amid Machine Clothing footprint optimisation.
Cash flow and balance sheet
Free cash flow rose to $36.5 million from $25.7 million a year earlier. Capital expenditure declined to $12.2 million from $18.3 million, while technical and research expenses increased to $12.2 million from $11.5 million. Albany ended the quarter with $79.1 million in cash and cash equivalents, total debt of $422.1 million and net debt of $343 million.
Fourth-quarter outlook
For the fourth quarter (Q4) of 2026, Albany expects consolidated net revenue of $325 million-$335 million. Machine Clothing revenue is projected at $170 million-$175 million and Engineered Composites revenue at $155 million-$160 million. The company expects adjusted EPS of $0.65-$0.75 and has revised its effective tax-rate estimate to 29.5 per cent from 31.5 per cent.
Fibre2Fashion News Desk (SG)